The IRS Set the 2027 Tuition Benefit Limit at $5,400. Most Employers Won't Notice.
November 12th, 2026
Part of the EFFA Tuition Benefits Brain Trust: Policy update. Last verified November 10, 2026. Sources are listed at the end.
What the first increase in the Section 127 limit since 1986 means for employers and schools, and why it was easy to miss.
The short version
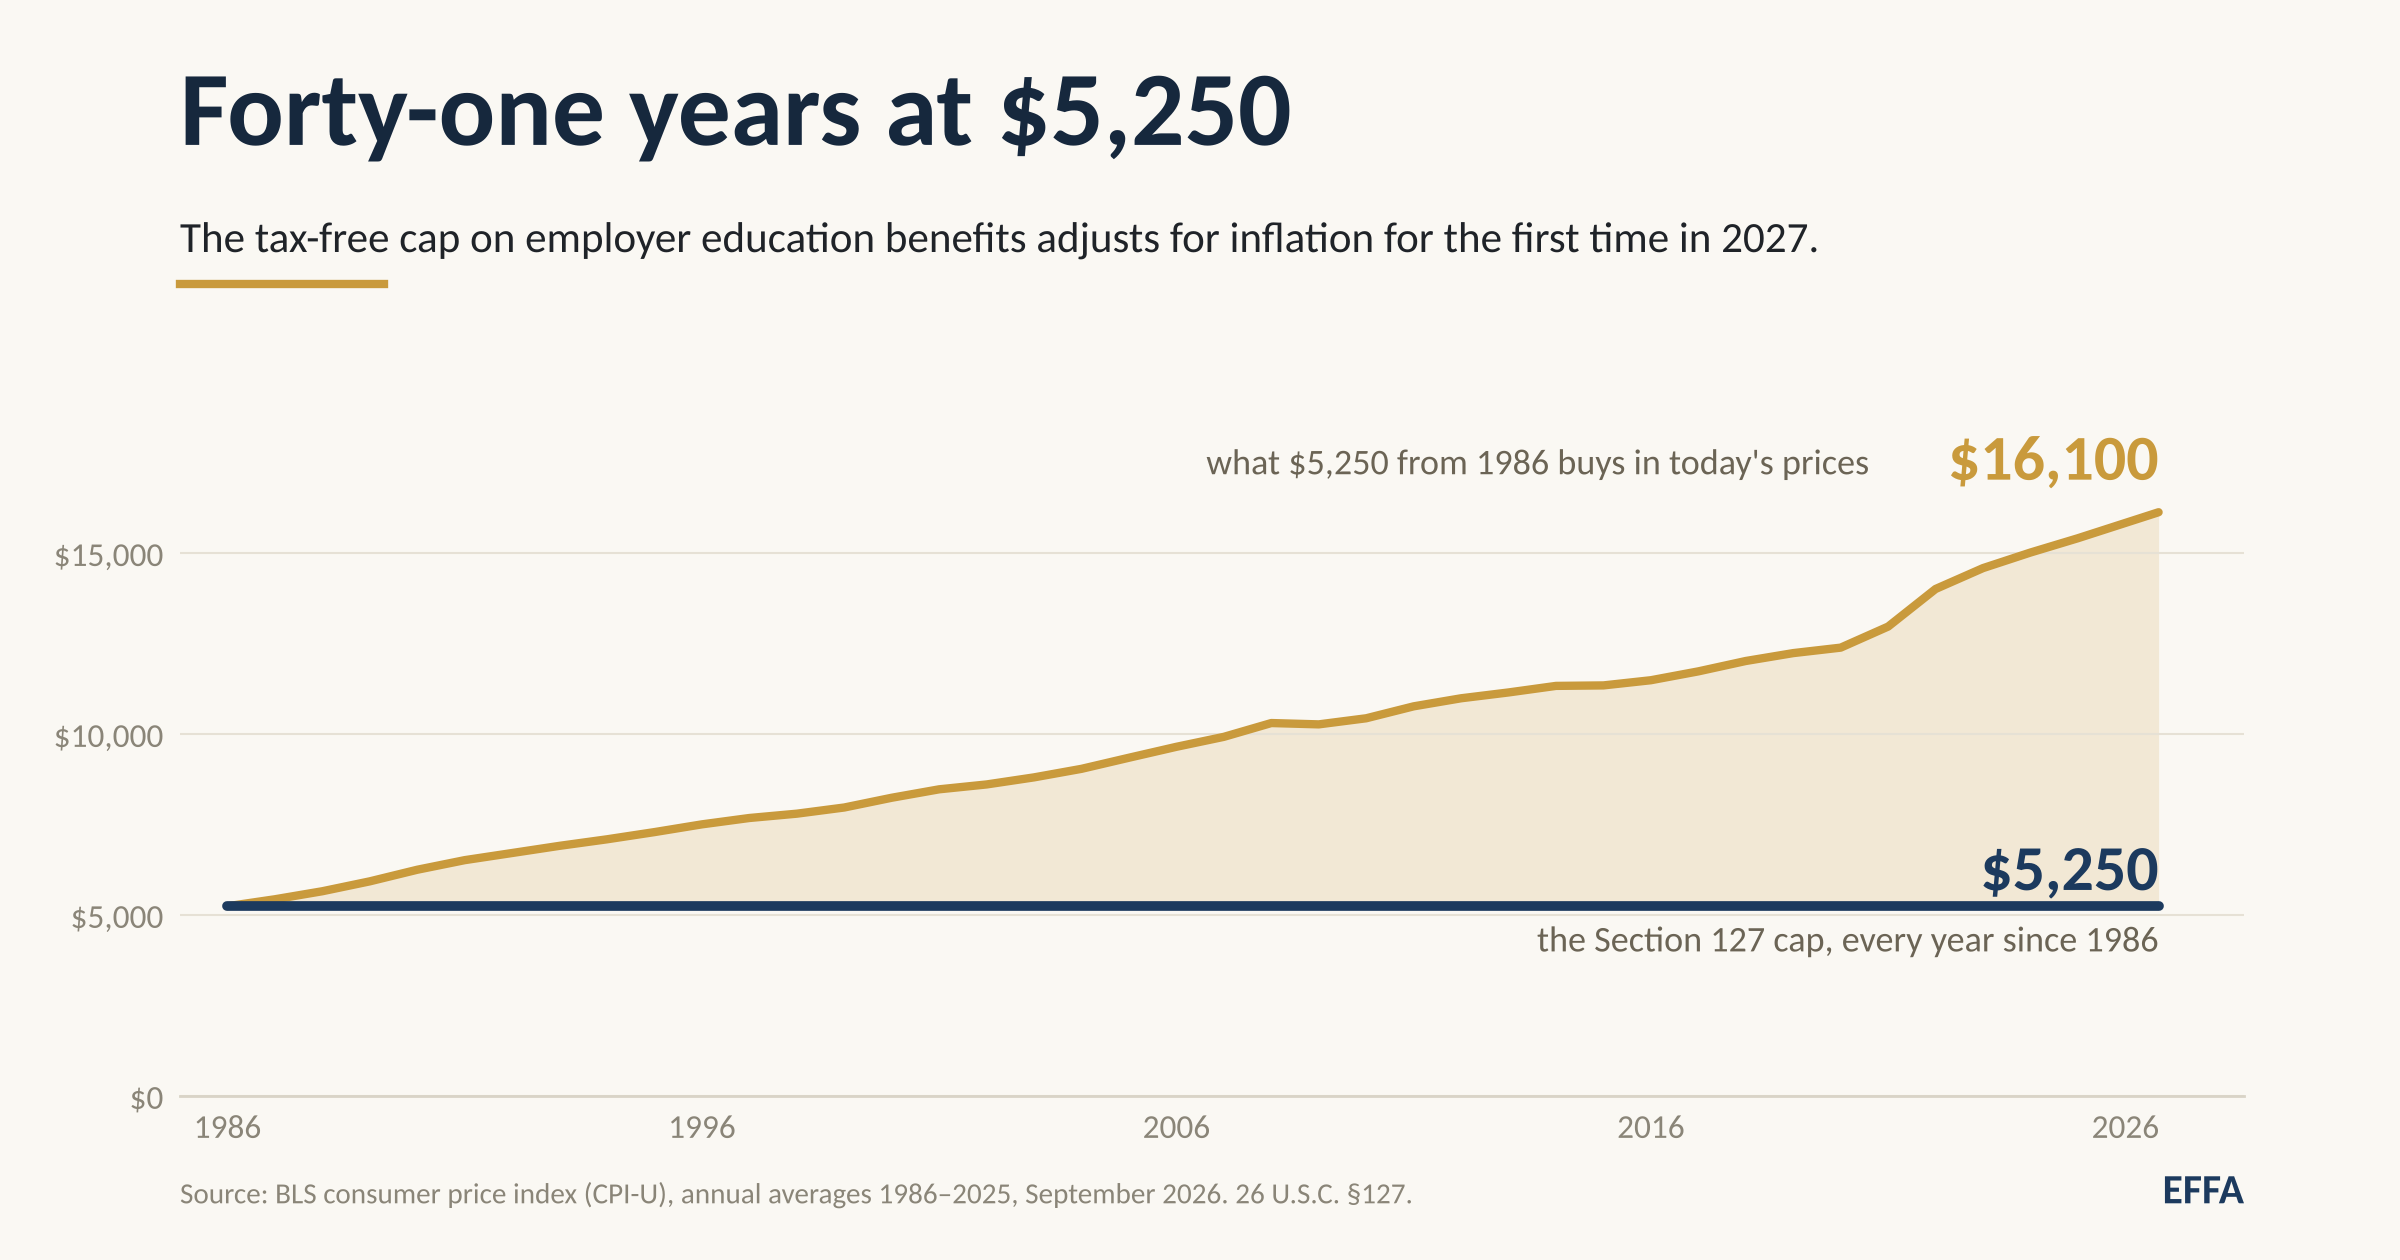
On November 5, 2026, the IRS set the 2027 tax-free limit on employer education benefits at $5,400, up $150 from $5,250. It is the first change since 1986. But the IRS's press release on the 2027 adjustments listed tax brackets, transportation benefits and flexible spending accounts, and did not mention it. The figure sits in section 3.17 of Revenue Procedure 2026-35. And none of the eight large education companies we tracked this earnings season mentioned Section 127 on their calls. A change this quiet won't reach most employees unless schools and employers explain it.
What changed (reported)
2027 limit: $5,400 per employee, for taxable years beginning in 2027. [Rev. Proc. 2026-35, section 3.17]
2026 limit: stays $5,250.
How it was set: the same inflation formula as the tax brackets, measured from 2025, rounded to the nearest $50. [26 U.S.C. §127; Public Law 119-21]
Student loan payments: still inside the same cap, and permanent.
What it means (our read)
The raise is small, but it now repeats every year. $150 is about 2.9%. What matters is that the cap moves with inflation from here on, after 41 years frozen.
Many plans won't move on their own. A plan written as "$5,250" keeps paying $5,250 in 2027 until it's amended. A plan written as "the Section 127 maximum" moves to $5,400 automatically.
It was easy to miss. The IRS headline release didn't mention it. Benefits teams that read headlines, not revenue procedures, won't know.
The operators didn't use it either. Phoenix, Strategic Education, Grand Canyon, Covista, Perdoceo, Bright Horizons, Lincoln Tech and American Public Education all talked about employers this season. None mentioned the change. The message is open for any school or employer partner to own.
So what
For employers: check whether your plan says "$5,250" or "the Section 127 maximum." Then decide whether to raise your benefit to $5,400. And ask how many eligible employees actually use it today.
For schools: update every page that says $5,250, and tell your employer partners before their benefits teams hear it elsewhere. The school that explains the change first gets the next conversation.
For direct-bill funding: a higher limit doesn't help an employee who can't front tuition and wait to be reimbursed. Paying the school directly is what turns the limit into enrollment.
Full details, including what the benefit covers and what an employer needs to offer it: What Is the Section 127 Limit for 2027?
EFFA helps schools and employers run employer-funded education, from partnership terms to payment. Request a demo.